Sometimes a deal does not start breaking because the buyer is unreasonable.
Sometimes it starts breaking because the seller never learned how to explain what actually happened in the business.
That sounds harsher than I mean it.
I do not mean the seller is lying.
I mean the seller is often too close to the business, too embarrassed by what happened, or too used to carrying the whole story in their own head. So when a buyer or a bank asks a simple question, the answer comes out fuzzy.
And fuzzy is expensive.
We are in a deal right now where the numbers are begging for a real explanation.
There were three sellers. One has already chosen to exit. Revenue was about $1.6 million in 2024, jumped to about $7 million in 2025, and 2026 is projected to land closer to $1 million.
We had a seller call.
We gave them room to explain.
We wanted the business story behind the swing.
What happened in 2025? Why was it such a fantastic year? What changed after that? What stopped? What remains? What could a new owner reasonably replicate?
We did not leave the call feeling confident.
We left feeling like there was still a missing narrative.
And when there is a missing narrative, the question in the buyer’s mind becomes, “What are they hiding?”
That does not always mean something sinister is happening.
Sometimes it means there is something painful or embarrassing behind the scenes. Maybe there was partner conflict. Maybe a key relationship broke. Maybe one person carried far more of the growth than anyone realized until they left.
But here is the point sellers need to hear clearly: buyers are not asking because they want gossip, and the bank is not asking because it wants a front-row seat to your personal life.
We are asking because we need to understand what happened in the business.
If revenue shot up and then fell off a cliff, we need to know why.
If one partner left and that person was the engine behind the stellar year, we need to know that too.
If the business can no longer produce what it produced before, that changes what it is worth and what kind of debt it can safely support.
A strange year does not automatically kill a deal. An unexplained year does.
When owners think about selling, they usually picture the buyer asking the hard questions.
That is true.
But the buyer is not the only audience that matters.
If a bank is involved, the lender has to believe the story too.
Not emotionally.
Practically.
They have to look at the last few years and decide whether this business can reliably service debt after closing.
That means buyers and banks are both asking some version of the same question:
Can this business produce enough dependable earnings in the future to justify the price and support the loan?
That is why a wild swing in revenue gets so much attention.
It is not just about whether one year was amazing.
It is about whether that year was real, repeatable, transferable, and still relevant.
If the explanation is strong, a strange year can be understood.
If the explanation is weak, buyers get conservative and banks do too.
That is how sellers end up shocked by the response they get from the market.
They think, But look how great 2025 was.
The buyer and lender think, We cannot lend against a story we do not understand.
This is where owners often get blindsided.
They assume an exceptional year will carry the valuation. Sometimes it does, but only if buyers and lenders believe the conditions behind it still exist or could reasonably be recreated.If they do not believe that, they protect themselves.
That protection can look like:
In the deal I mentioned earlier, we are moving forward with an LOI, but it is for about half the asking price. It also includes a fairly large forgivable seller note tied to revenue. If revenue never rebounds even to the historical 2024 level, the note is entirely forgiven. And, we completely excluded 2025 revenue as an outlier, which means the sellers are getting no credit in the purchase price for all that hard work.
That is not because buyers enjoy being stingy. It is because when the story behind the numbers is weak, the structure has to absorb the risk. And if the bank cannot get comfortable, the deal gets even tighter.
This is one of the biggest mistakes sellers make. They think a buyer’s caution is personal. Often, it is just underwriting.
Here is where this gets especially tricky.
A lot of owners assume certain details are private and irrelevant.
They think, That was just partner drama. That shouldn’t matter.
And to be fair, buyers do not need every detail.
No one is asking for your private text messages or a blow-by-blow account of who upset whom at the management meeting.
But if the so-called drama changed the business, then it matters.
A lot.
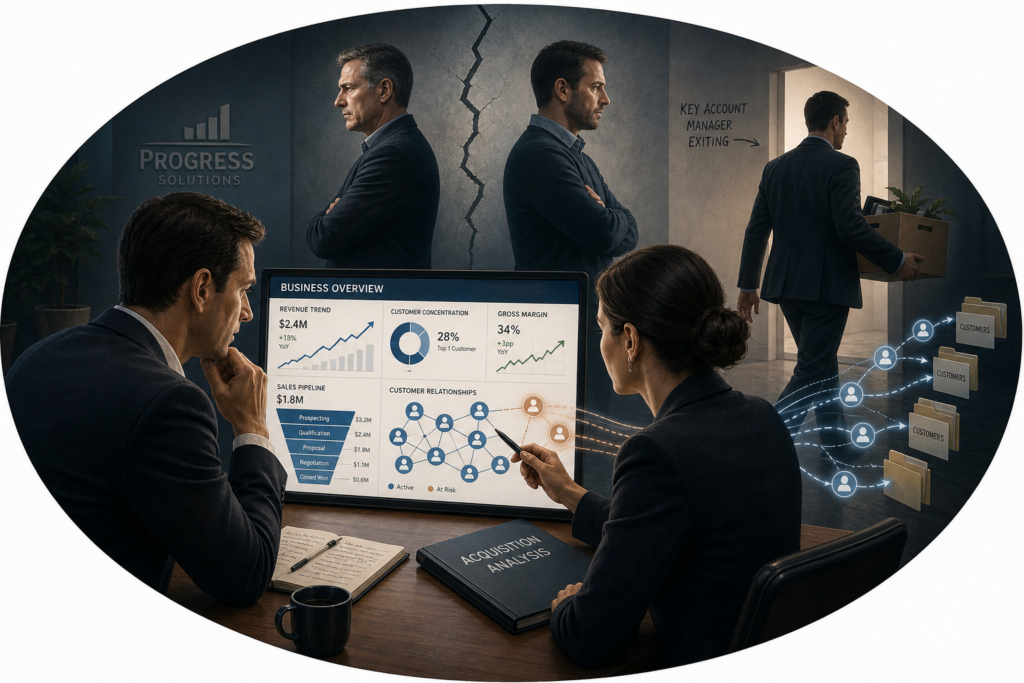
Maybe one partner was the one bringing in the big accounts.
Maybe one partner built the channel that drove the huge year.
Maybe one partner carried the relationships, sales process, or execution muscle that made the numbers possible.
If that person is gone, that is not just personal drama anymore.
That is business impact.
Buyers do not care about the drama itself.
Banks do not care either.
But both care very much if the person who drove the $7 million year walked out the door.
Now the question becomes:
Can this performance be replicated without that key person and their relationships?
That is not nosiness.
That is risk analysis.
This is also where transparency becomes so important.
When sellers separate personal drama from business impact in their own minds, but never connect the dots out loud, they leave the buyer and the bank to do it themselves.
And they will usually do it in the most conservative way possible.
I want to be careful here, because this is where some owners shut down. They hear transparency and think they need to present themselves as flawless.
They do not.
You do not need a perfect three-year run.
You do not need every year to be smooth.
You do not need to pretend there were no hard seasons, no failed experiments, no customer losses, no team turnover, and no ugly moments between partners.
What you do need is a coherent story.
That means being able to explain, in plain language:
Notice what is not on that list:
You do not have to overshare personal details.
You do not have to defend every emotion.
You do not have to make yourself look good.
You just have to help an outsider understand the business reality.
That is what builds trust. Not polish. Not spin.
Clarity.
What buyers and banks are actually trying to understand
When a business has a big spike followed by a drop, the buyer and lender are trying to answer practical questions.
Questions like:
Those are not cruel questions. They are normal questions.
And if the seller cannot answer them clearly, buyers and banks start filling in the blanks for themselves.
That is when a fantastic year gets treated like it never happened.
This is where many sellers get themselves into trouble without meaning to.
They know something meaningful happened, but they explain it in a vague, defensive, or incomplete way.
They say things like:
None of those statements are useful on their own. They may even be true. But they are not enough.
Do you feel the difference?
Those explanations are not polished in a corporate way.
They are just honest.
They connect the human events, operating reality, and financial outcome.
That is what buyers and banks need.
Early in a deal, buyers will often keep moving as long as there is a plausible path to clarity. That is normal.
A letter of intent is not the finish line. It is the start of a deeper fact-finding process.
So yes, a buyer may submit an LOI while still having major questions.
They may structure around the uncertainty.
They may give the seller a chance to prove the narrative in due diligence.
But if due diligence arrives and the story still does not come together, many buyers will walk. I would.
Not because I need perfection.
Not because I expect sellers to have never made mistakes.
Not because I am judging their personal life.
I will walk because if I cannot get a good, full narrative that makes business sense, then I cannot underwrite the future with confidence.
And if I cannot do that, I should not close.
The bank will reach the same conclusion in its own language. It may not say, We think you are hiding something. It will simply refuse to underwrite a business with earnings it cannot explain and cash flow it cannot trust.
That is why sellers need to stop treating transparency like a soft skill.
It is deal skill.
If you are a few years away from selling, this is good news. You have time.
You do not need to wait until a buyer is staring at your P&Ls to start telling the story behind your numbers. You can begin now.
A few practical steps you can take:
The goal is not to build a dramatic presentation.
The goal is to make sure your future buyer and their bank do not have to guess.
The more clearly you can explain your own business, the less likely someone else is to discount it, over-structure it, or walk away from it.
If any part of this hit a nerve, you are not alone. Most owners have never had anyone explain how buyers and banks actually hear their story.
They think the numbers will speak for themselves. Often, they do not.
If you want practical, no-jargon guidance on how to explain your numbers, reduce risk before a sale, and see your business through a buyer’s lens, join my email list. There, I share the step-by-step view from the other side of the table, in normal language, before the stakes get high.
Click here to join the HCW Biz Advisors email list and start getting better at telling the real story behind your business long before you are sitting in a seller call with money on the line.
Heather Williams is a small business buyer and founder of HCW Biz Advisors. Alongside her husband Chris, she evaluates and pursues small business acquisitions while helping owners of established, service-based businesses get buyer-ready years before they are ready to exit.
